
Introduction[1]:
Stock exchange by its nature is volatile. It has become a routine for various investors to study the market and wonder how to cover up their losses as quickly as possible. It must occur to some of us that it would be so much easier to recover those losses if they had a little more information about the financial situation of the company, they have invested in.
Insider Trading concept exists in India long back since 1940s. The Sachar Committee, Patel Committee and the Abid Hussain Committee all made suggestions for a separate statute governing insider trading because of the Companies Act of 1956’s insufficient enforcement mechanisms.
Offences of insider trading have gained momentum and importance after high profile cases such as Infosys, Reliance, Rakesh Jhunjhunwala (Aptech case) have come into forefront and have been pursued by SEBI.
But the question arises, is knowing such inside information and insider trading is legal in India or not. If not, then how to determine what is Insider Trading.
It is to be pondered whether merely knowing any information, and acting on the same, shall be a cognisable offence. The concept of mens rea or the intention to act comes into picture when accessing the situation of insider trading, and this article analyses this specific aspect.
Insider Trading:
Insider trading consists of an individual having access to information which is not known to the general public but is known to a few people who might have access to the information purely based on position, chance or wrongful act of obtaining such information. Such people then buy or sell securities in order to either make profit or prevent any future loss which is predicted or envisaged by them on the basis of such non-public information, that shall occur if the information known by the person becomes public knowledge. It is a misconception that insider trading is done only for the purpose of earning profit. In certain cases, it can also be indulged in to avoid losses and as the saying goes “Money saved is money earned”, the stop losses become a pseudo-profit for the person indulging in insider trading.
Example: Mr. X is an employee in a crucial department in ABC company. He is aware that ABC Company is indulging in fraudulent activities. He then, on the basis of this information, sells his shares before the public information comes into limelight. This is known as insider trading, where an individual has taken undue advantage of a non-public information.
Insider Information vs Insider Trading:
Insider Trading should not be confused with Insider Information. Insider Information implies merely knowing something about a financial position or any other trade related information of an organization but not making any use of that information for making profit or preventing loss.
Merely knowing Insider Information of an organization is not a chargeable offence under the law but making use of such information for making profit or preventing loss is considered as a chargeable offence.
Legal Provisions related to Insider Trading:
Currently, the provisions relating to Insider Trading in India are governed by Securities Exchange Board of India (SEBI) Regulations, 1992, SEBI (Prohibition of Insider Trading ) Rules, 2015 and many other regulations. The term “Insider Trading” is defined under The SEBI(Prohibition of Insider Trading Rules) 2015 and any amendments thereof (“Regulations”) defines who will be considered as an Insider under the law and also touches upon other important key concept, which are as follows:
“Insider” means any person who is:
- a connected person; or
- in possession of or having access to unpublished price sensitive information. (Regulation2(d))
“Unpublished Price Sensitive Information” means any information relating to a Company or its securities, directly or indirectly that is not generally available which upon becoming generally available, is likely to materially affect the price of the securities and shall, ordinarily including but not restricted to, information relating to the following:-
- Financial Results.
- Dividends.
- Change in Capital Structure.
- Mergers, de-mergers, acquisitions, delistings, disposals and expansion of business and such other transactions.
- changes in key managerial personnel.
It is intended that information relating to a company or securities, that is not generally available would be unpublished price sensitive information if it is likely to materially affect the price upon entering into the public domain.
The Regulation 3(1) of The SEBI(Prohibition of Insider Trading) Regulations,2015 [2]provides that No insider shall communicate, provide, or allow access to any unpublished price sensitive information, relating to a company or securities listed or proposed to be listed, to any person including other insiders except where such communication is in furtherance of legitimate purposes, performance of duties or discharge of legal obligations. It implies Insider Trading or Trading on the basis of Insider Information is illegal except for the furtherance of legitimate purposes or for performing a duty or for discharging any legal obligations.
“Connected Person generally includes but is not limited to a holding, associate , subsidiary company, limited company, trust company, asset management company, member of the board of directors, employee, banker of the company, concern, firm, trust, Hindu Undivided Family company or association of persons wherein a director of a company or his immediate relative or banker of the company, has more than ten per cent of the holding or interest or even a relative of any person considered as connected persons.
In this article we are going to examine how the concept / doctrine of Mens Rea will have an impact on Insider Trading through the Judgement passed by Apex Court i.e., Securities Exchange Board of India (SEBI) versus Abhijit Rajan(Civil Appeal No. 563 of 2020).
Background of the case:
Abhijit Rajan was the Chairman and Managing Director of the Company ‘Gammon Infrastructure Private Limited’ (GIPL) . Gammon Infrastructure private Limited is listed on the Bombay Stock Exchange. Mr. Abhijit Rajan continued to be the chairman till September 20,2013. And later on, ceased to be a Managing Director of the Company but he continued to be in the position of being a Director in the Company. In 2012, GIPL entered into a Contract with National Highway Authorities of India whose cost was Rs. 1,648 crores. Another company named Simplex Infrastructure Limited (SIL) was also awarded a contract whose cost was Rs. 940 crores. GIPL and SIPL were both companies which will have to make investments in Special Purpose Vehicles created by each other. The investments were to be made in such a manner that both the companies will hold 49% shares in each other.
Chain of events leading up to the accusations of Insider Trading is as follows:
For the purpose of procuring the above-mentioned special purpose vehicles, both companies set up a specific Special Purpose Vehicle. The company ‘GIPL’ set up a Special Purpose Vehicle by the name of Vijayawada Gundugolanu Road Project Private Limited (“VGRPPL”).The Company ‘SIL’ set up a Special Purpose Vehicle by the name of Maa Durga Expressways Private Limited (MDEPL).
The deal of setting these vehicles was carried out in such a manner that both companies- GIPL and SIL were holding 49% interest in each other. However,
- On 09.08.2013: the Board of Directors of GIPL passed a resolution authorizing the termination of both shareholders agreements.
- On 22.8.2013, the Respondent(Mr. Abhijit Rajan) sold about 144 lakhs shares (approx.) held by him in GIPL, for an aggregate value of approximately Rs. 10.28 crores.
- On 30.08.2013 GIPL made a disclosure to the National Stock exchange of India and BSE regarding the termination of two shareholders agreements.
- On 20.09.2013 the Respondent resigned from the post of Chairman and Managing Director of GIPL.
The cancellation of the above shareholder’s agreements had put GIPL in advantageous position and thus it was a reasonable expectation that the share prices of GIPL would shoot up. The Respondent, Mr. Abhijit Rajan could have waited to sell shares of GIPL till the news of cancellation of Shareholder’s Agreements is made public. Inspite of such situation, the respondent, Mr. Abhijit Rajan sold the shares beforehand which indicates absence of any intention to make use of the information for making any illicit profit. It is important to note that the respondent,
Chain of events leading up to the accusations of Insider Trading is as follo Mr. Abhijit Rajan had to prevent the parent company from going bankrupt and it would be favourable for the respondent to wait until the information was out. The sale of shares before the unpublished information was published was enough to denote this transaction as a distress sale, devoid of any intention of earning unlawful gains.
The Dispute in question was whether these transactions by Mr. Abhijit Ranjan (Responder) will be considered as an Insider Trading? And whether Mens Rea played an important role in concluding if this case falls under Insider Trading.
JUDGEMENT:
The Supreme Court held that:
While determining whether a particular transaction is to be considered as an Insider Trading or not, the following conditions need to be checked:
- The Individual must be an Insider as per the law.
- The information possessed by such individual shall be considered as Unpublished Information.
- The nature of information is such that it is price Sensitive within meaning of Section 2(h) of the SEBI (Prohibition of Insider Trading regulations) 2015.
- The Individual must have committed Insider Trading by dealing in the securities.
The Hon’ble Court concluded that Mr. Abhijit Rajan was fulfilling all the above conditions. However, it was important to consider the aspect of Mens and common human conduct while determining the verdict.
In this case, the prices of the shares shot up after Unpublished Information was published. However, Mr. Abhijit Rajan had already sold off his shares before publishing of such unpublished information. He did not earn profit from those shares because of the information known to him beforehand. On the contrary he suffered loss as a result of the transaction. Any person willing to earn profit would not sell the shares before such information was published. The sale in this case was considered distress sale and the Hon’ble Court held that Distress Sale is not similar to the sale of Insider Trading. Any person desirous of Insider Trading would have waited till the information went to public to sell his shares.
The Hon’ble Court dismissed the appeal of SEBI on the above-mentioned grounds.
Conclusion
The above interpretation led to a deviation in the approach towards Insider trading which is distinct from the judicial trend[3] where Mens Rea was not considered important for imposing SEBI regulations, and it was stated that section 15G of The Securities and Exchange Board of India Act, 1992 does not attract the criminal penalty and therefore Mens Rea was not considered while arriving at the decision. The Securities and Exchange Board of India Act, 1992 provides for various penalties for offences pertaining tosecurities, wherein specifically Section 15G of The Securities and exchange Board of India Act,1992 states the penalties for Insider Trading. If a person indulges trading of securities while being aware of the Unpublished Price Sensitive Information , the following provisions shall apply:
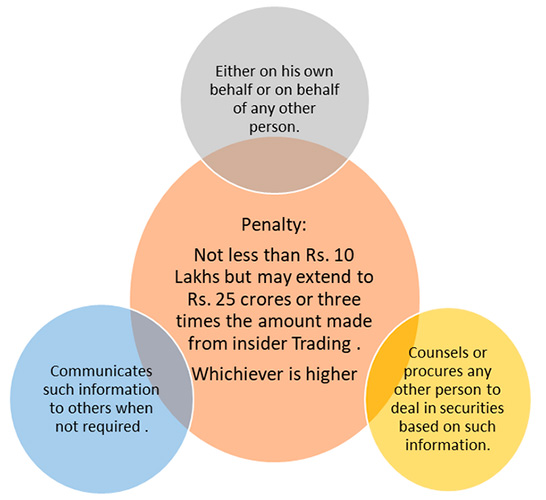
- The article reflects the general work of the authors and the views expressed are personal. No reader should act on any statement contained herein without seeking detailed professional advice.
- The SEBI(Prohibition of Insider Trading) Regulations,2015
- SEBI versus Cabot International Capital Corporation(Appeal No. 7 of 2001 in SEBI Appeal No. 24 of 2000)
For any feedback or response on this article, the authors can be reached on Shreya.Godse@ynzgroup.co.in and shruti.kulkarni@ynzgroup.co.in
Author : Shreya Godse
Ashvini is a Partner- Corporate Legal Advisory, She is experienced in corporate litigation and non-litigation. She is experienced in Corporate litigation and non- litigation. She provides training required under POSH Act.
Co-Author : Shruti Kulkarni
Ayushi is experienced in corporate legal and heads the investment and deal advisory at YNZ Legal. She is also a member of Bar Council of Maharashtra & Goa. By qualification she is Master in Commerce and Bachelor of Law from Mumbai University.