
It was recently reported that a Show Cause Notice was issued to cryptocurrency exchange Zanmai Labs Pvt Ltd, known as WazirX and its directors under FEMA for transactions involving cryptocurrencies worth Rs. 2,790 crore. This can be said to be one of the several cases under ED’s investigation related to crypto currency frauds wherein a few crypto exchanges were allegedly found to be involved in money laundering.
The Press Information Bureau indicates that as on 31.01.2023, the Directorate of Enforcement had issued notices for attaching/seizing/freezing the proceeds of crime amounting to Rs. 936 crore [1].
While the investigation and arrests under such cases have been carried out under the Prevention of Money Laundering Act 2002 (“Act”), there wasn’t a specific provision covering the crypto/virtual digital assets up until now.
The Virtual Digital Assets (“VDA”) are now covered under the purview of Prevention of Money Laundering Act, 2002 (“Act”), as per notification dated March 07, 2023 by Ministry of Finance [2].
WHAT ARE VIRTUAL DIGITAL ASSETS?
The meaning of VDA is set forth in Income Tax Act, 1961 to include:
- any information or code or number or token generated through cryptographic means (by whatever name called, providing a digital representation of value exchanged with or without consideration, with the promise or representation of having inherent value, or functions as a store of value or a unit of account including its use in any financial transaction or investment, but not limited to investment scheme; and can be transferred, stored or traded electronically); or
- a non-fungible token or any other token of similar nature, by whatever name called; or
- Any Other Digital Asset as the Central Government may decide
EXAMPLES OF VIRTUAL DIGITAL ASSETS:
- Cryptocurrencies like Bitcoin, Ethereum, stable coins etc.
- Non-Fungible Tokens (NFTs)
Impact Assessment on Business:
- Under the Act, the role of reporting entities such as banks, financial institutions, intermediaries and persons carrying on designated business or profession is defined for prevention of money laundering
- Persons carrying on designated businesses or profession under current context may include crypto exchanges, intermediaries, service providers etc.
PERSONS CARRYING ON DESIGNATED BUSINESS OR PROFESSIONS:
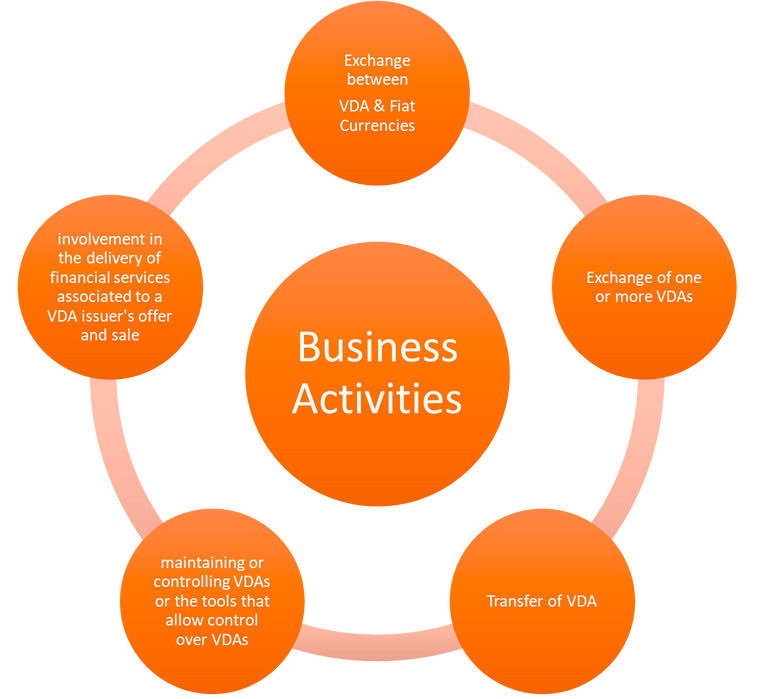
Hence as per the current notification, the VDA service providers and designated businesses can now be said to be included as “Reporting Entities” and seem to be subject to the same reporting requirements and Know Your Customer (KYC) requirements as other regulated organizations like banks, securities intermediaries, payment system operators, etc. are required to adhere to.
These Compliances may include:
- Maintenance of Records
- All transaction
- The information of such transaction shall be furnished to the Director under the Act Records to be maintained evidencing identity of its clients and beneficial owners account files and business correspondence relating to its clients.
- The information and records shall be kept confidential
- These records shall be maintained for 5 years subject to some condition.
- Verification of Identity
- Authentication under Aadhar
- Offline verification under Aadhar
- use of passport issued
- use of any other officially valid document or modes of identification
- Enhanced Due Diligence
- Verified the details and identity of every client before processing of any specified transaction[3].
- Additional steps to be taken to examine ownership, financial position, source of funds, also record the purpose behind the specified transaction
- If such transaction is suspicious, Reporting Entity to increase the monitoring of such entity
- This is to be maintained for 5 years currently.
PENALTIES UNDER THE ACT:
Section 13 (2) of the Act states that if Director finds that the Reporting Entity has failed to comply with the obligations specified under Section 12 with respect to maintenance of records then Director shall!impose fine on Reporting Entities which shall not be less than Ten Thousand Rupees which may, extend to One lakh Rupees for each failure.
Under Section 14 currently there are no Civil or Criminal proceeding against the Reporting Entities including their officers in certain cases as defined under the Act.
Impact Assessment on Individuals/ Beneficial Owners:
REPERCUSSIONS UNDER THE ACT:
As per Section 4 of the Act, Whoever commits the offence of money-laundering shall be punishable with rigorous imprisonment for a term which shall not be less than Three years, but which may extend to Seven years and shall also be liable to fine
Further, as per Section 5 of the Act, the Director under the Act, also has a right of attachment of property by an order for a period not exceeding One Hundred and Eighty Days from the date of the order, in such manner as may be prescribed.
- Transacting in crypto currencies and/or owning and transferring other crypto assets which up until now required minimal information of the individual owners.
- This scenario will certainly change now with potential increase in compliances which will demand more information specially to identify the beneficial owners
- VDAs being recently covered under the tax regime as well as money laundering legislation certainly increases accountability and responsibility of the individuals dealing in VDAs.
- However, considering the recent developments in the legislation, the general picture in India seems to be towards regulation of crypto assets, which would promote responsible compliance and regulation culture in VDA arena.
- Additionally, requisite checks and balances are now in place to ensure the sovereignty of the country and to strengthen the efficacy of anti-terror systems.
- https://pib.gov.in/PressReleseDetailm.aspx?PRID=1896722
- https://egazette.nic.in/WriteReadData/2023/244184.pdf
- Section 12AA of the Act
For any feedback or response on this article, the authors can be reached on Ayushi.Kalelkar@ynzgroup.co.in or sanika.phatak@ynzgroup.co.in or siddhi.mhamunkar@ynzgroup.co.in
Author : Siddhi Mhamunkar
Siddhi is an associate at YNZ Legal. By qualification she is a Bachelor in Commerce and Bachelor of Law from Mumbai University.

Co-Author : Ayushi Kalelkar
Ayushi is experienced in corporate legal and heads the investment and deal advisory at YNZ Legal. She is also a member of Bar Council of Maharashtra & Goa. By qualification she is Master in Commerce and Bachelor of Law from Mumbai University.
Co-Author : Sanika Phatak
Sanika is an associate at YNZ Legal. By qualification she is Master in Corporate Law from Vishwakarma University, Pune and Bachelor of Law from Pune University.