
Introduction:
Attention MSMEs [1], 4 cases have been successfully resolved out of 9 which were admitted under Pre-Packaged Insolvency Resolution Process.[2] (PPIRP). A new safer Route for all the small business who are distressing for losing their control over management. But why should MSMEs choose PPIRP over the traditional Corporate Insolvency Resolution Process (CIRP)? Let’s explore the compelling reasons that make PPIRP the smarter choice for MSMEs looking for financial turnaround.
| CIRP | PPRIP |
|---|---|
| 1. Eligibility Criteria for Initiation | |
| ● CIRP can be initiated by: 1. Financial Creditors 2. Operational Creditors 3. Corporate Debtors themselves ● CIRP can be initiated against all the corporate persons whose default is not less than Rs. 1 cr which includes: 1. All companies registered under companies Act 2013 or any other previous act 2. All companies registered under any special Act 3. All Limited Liability partnerships (LLPs). 4. Personal Guarantor of a corporation debtor. ● To initiate the process, the applicant must submit the required forms along with a fee of ₹25,000 to the National Company Law Tribunal (NCLT). | ● PPIRP can be initiated only by corporate debtor itself who must be classified as MSMEs having minimum default in payment of Creditors of Rs. 10 lakhs. ● To initiate the process, the applicant must submit the required forms along with a fee of ₹15,000 under section 54c \of IBC 2016 To the National Company Law Tribunal (NCLT). |
| 2. Time Limit | |
| ● The CIRP must be completed within 180 days from the commencement date, a one-time extension can be granted upto 90 days by NCLT, making a total of 270 days. ● In exceptional cases like any legal proceedings further extension can bring the maximum timeline to 330 days. This extension is discretionary. | ● Unlike CIRP, this method offers a quicker and more efficient route to resolve insolvency which involves submitting a Base Resolution Plan alongside the initiation application. ● The Committee of Creditors (CoC) needs to approve the resolution plan within 90 days from the PPIRP commencement date. This includes evaluating the base resolution plan and any other competing plans and within next 30 days the plan must be approved by NCLT ● This entire process shall be completed within 120 days from the commencement date. |
| 3. Appointment of Resolution Professional (RP) | |
| ● Upon initiation of CIRP, an Interim Resolution Professional (IRP) is appointed by the NCLT to take control of the corporate debtor’s management. The IRP assumes all powers of the board of directors and oversees the company’s operations. He constitutes the Committee of Creditors (CoC) within 30 days of initiation. ● CoC may replace the Interim Resolution Professional (IRP) with another Insolvency Professional (IP) to act as the Resolution Professional (RP). Alternatively, the IRP may continue in the role of RP. ● RP is responsible for running day-to-day operations of the corporate debtor as going concern and to manage the process of CIRP. | ● In PPIRP, there is no provision for an Interim Resolution Professional. Instead, a Resolution Professional is appointed directly upon receiving approval from 66% of creditors in a meeting and his role is more supervisory as compared to the IRP/RP in CIRP. ● RP monitors the process to ensure compliance with the provisions of IBC 2016,and assists in facilitating the resolution plan, However, the Committee of Creditors (COC) can pass a resolution to authorize the RP to manage the Corporate Debtor’s operations. |
| 4. Management of Corporate Debtor | |
| ● The IRP/RP takes over full control of Corporate Debtor, replacing the board of directors and managing all aspects of the company’s operations. ● In CIRP all the powers of BOD are suspended, and everything is controlled and managed by IRP/RP. ● Existing promoters and management cannot participate in the resolution process during CIRP. (As per Judgement of Supreme Court in case Bank of Arun Kumar Jagatramka Vs Jindal Steel And power Ltd.) [3]. | ● The existing management retains control of the corporate Debtor, with the insolvency professional providing oversight and ensuring regulatory compliance. ● In the PPIRP, the erstwhile management has an opportunity to submit resolutions plan i.e Base Resolution plan and resolve the insolvency of company by keeping the same management. |
| 5. Approval of Resolution Plan | |
| ● RP invites the Prospective Resolution applicants to submit their Resolution Plans, he evaluates received plans and presents them to the Committee of Creditors (CoC). COC reviews these plans based on feasibility, viability, and the potential to maximize asset value and approves a plan with 66% votes. ● From all the plans presented before the COC The plan that gets the most votes from the COC, with at least 66% in favor, will be approved. ● If none of the plans receives the required 66% votes the plan with the highest voting will be subject to a revote. If this plan secures 66% or more votes during the revote, it is approved and presented before NCLT for final approval. After the approval of NCLT the process of CIRP is successfully completed. | ● In PPIRP if Base Resolution Plan does not impair Operational Creditors, then COC may directly approve the plan with minimum 66% votes in favour and it will be submitted to NCLT for approval. ● However, if the Base Resolution plan impairs Operational Creditors or COC is not satisfied by Base Resolution Plan, RP invites the Resolution plan from other Resolution Applicants and select one plan as Best Alternate Plan(BAP). ● When the BAP is received, the Corporate Debtor (CD) can improve its plan to compete with the BAP. This competitive process allows both plans to challenge each other. The winning plan form this process is then submitted to the National Company Law Tribunal (NCLT) for approval. |
| 6. Failure | |
| ● If CIRP fails with no approved plan by COC, the NCLT mandates company’s liquidation. | ● If PPIRP fails, the company has option to initiate CIRP for resolution of insolvency instead of mandatory liquidation. |
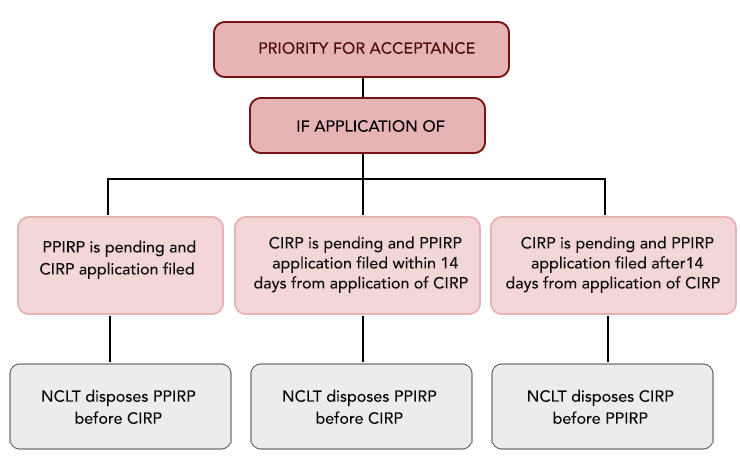
Conclusion:
CIRP & PPIRP both are integral to the Insolvency and Bankruptcy Code (IBC), yet they serve distinct purposes and cater to different scenarios. CIRP, provides a structured and judicially overseen mechanism, a creditor-driven approach to resolve insolvency and liquidation cases. In contrast, PPIRP, is a quicker, debtor-initiated alternative designed primarily for Micro, Small, and Medium Enterprises (MSMEs). The lower threshold for initiating PPIRP and reduced costs make it a more accessible option for MSMEs. Furthermore, the emphasis on a base resolution plan gives existing management a chance to rebuild their own business instead of giving control to someone else. Therefore, MSMEs should consider PPIRP as a preferable alternative to CIRP to navigate insolvency more effectively and sustain their business continuity.
- The article reflects the general work of the authors and the views expressed are personal. No reader should act on any statement contained herein without seeking detailed professional advice.
- Insolvency and Bankruptcy Board of India ( ibbi.gov.in)
- Arun-Kumar-Jagatramka-Vs-Jindal-Steel-and-Power-Ltd.-Supreme-Court-of-India.pdf (taxguru.in) (Refer D1)
For any feedback or response on this article, the authors can be reached on cstrainee@ynzgroup.co.in and cstrainee1@ynzgroup.co.in
Author : Sukhada Ballal
Sukhada is a CS trainee at Kalyani Oak and Associates. She is pursuing the
professional program of Company Secretary, by qualification, she is Bachelor of Commerce from R.A. Podar of Commerce and Economics.
Co-Author : Siddhi Gagangras
Siddhi is a CS trainee at Kalyani Oak and Associates. She is pursuing Company Secretary Course. By qualification she is a Bachelor of Commerce from Mumbai University.